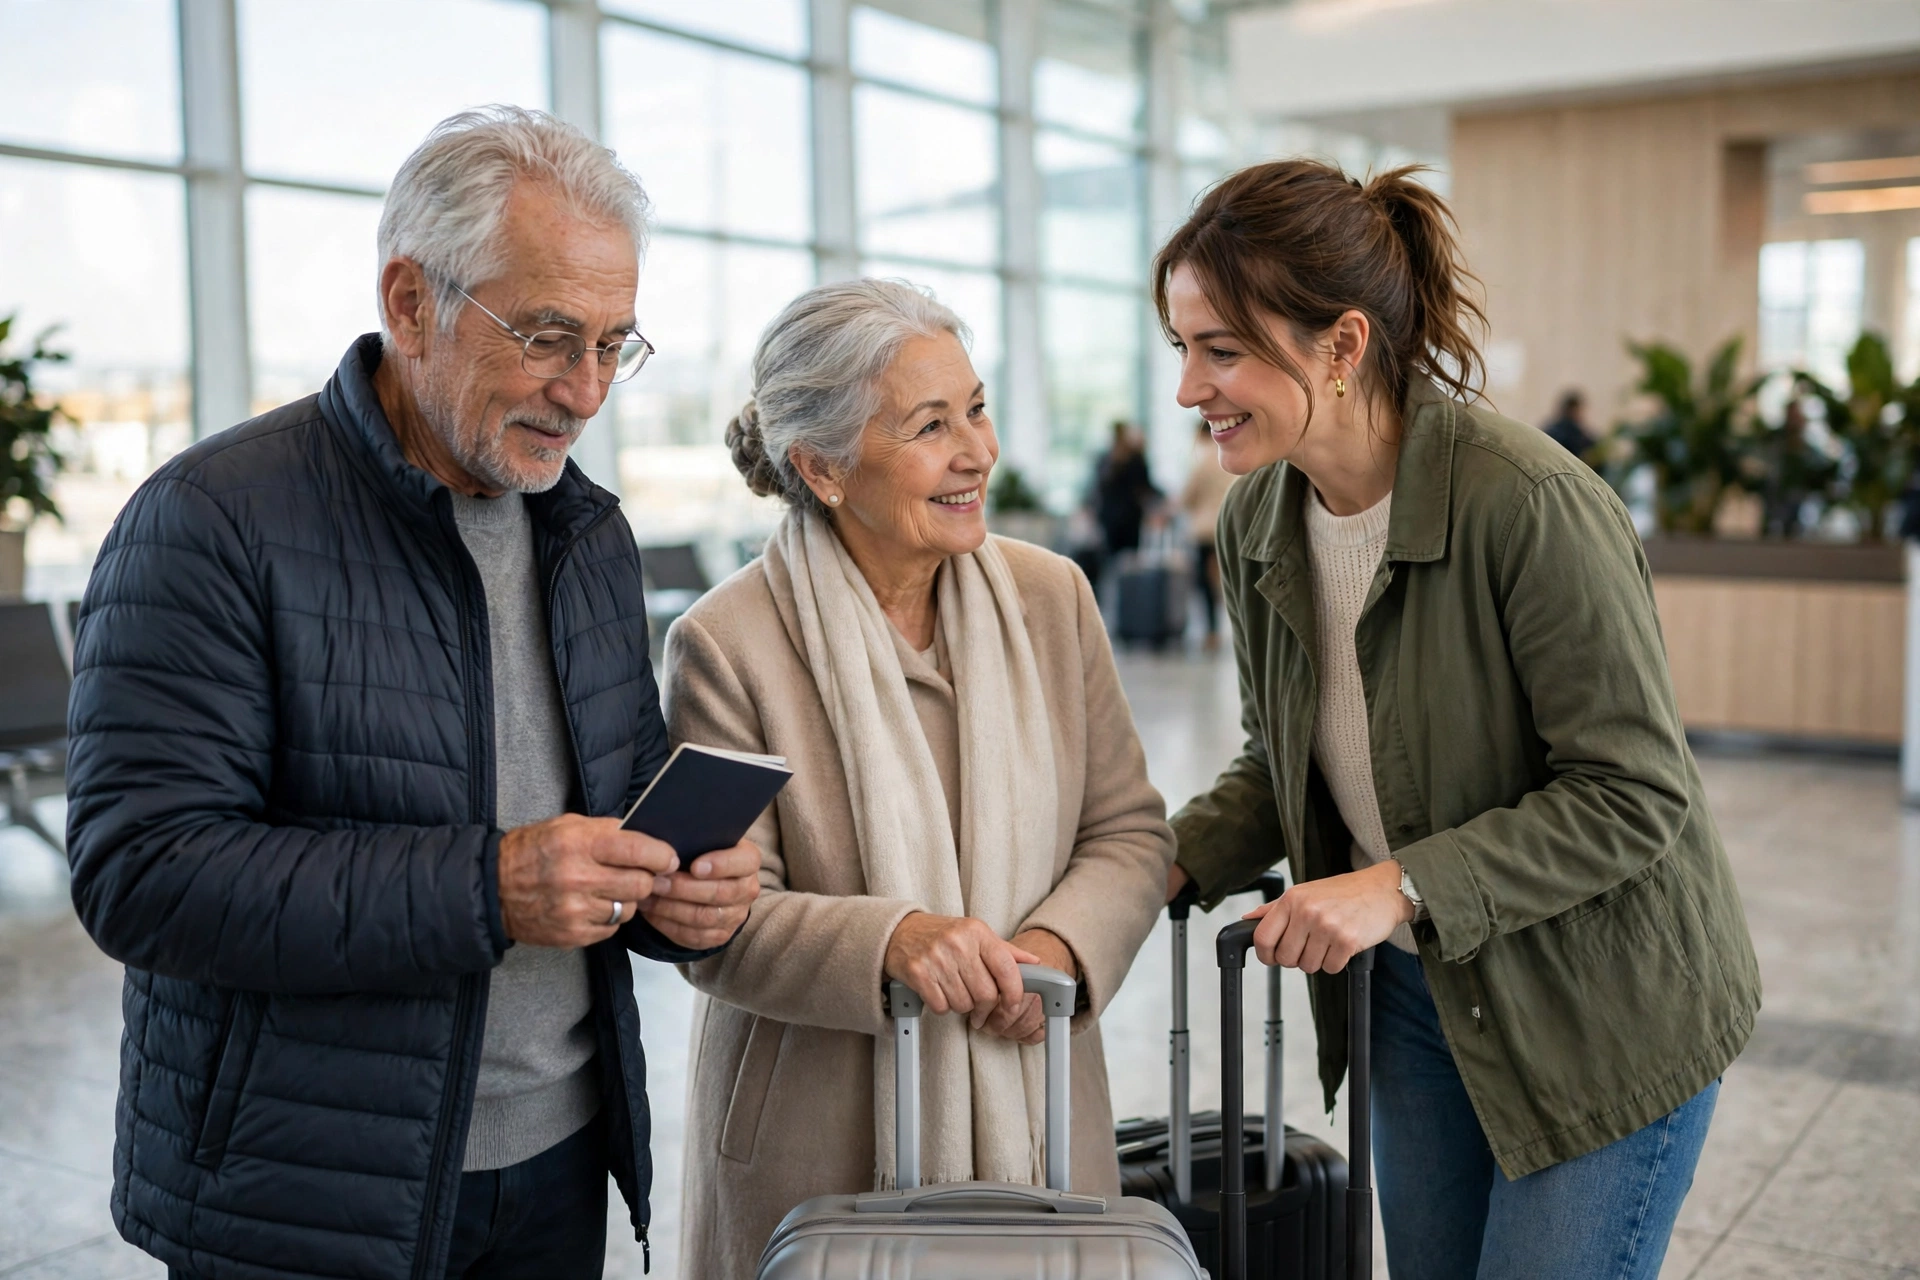
Picture this: you are at the airport check-in desk, your mum is holding her passport a little too tightly, and your dad is quietly wondering whether his heart medication is in the hand luggage or the suitcase. The trip is finally happening — and the one thing standing between excitement and worry is a question you have been putting off. What happens if one of them falls ill far from home? Choosing the right travel insurance for a trip with elderly parents is not about finding the cheapest policy. It is about making sure a medical emergency abroad becomes a manageable problem, not a crisis.
Start With Your Parents’ Health, Not the Price
Before you compare a single policy, sit down with your parents and make an honest list: every current condition, every medicine with its dose, any hospital visit in the last couple of years, mobility limits, and allergies. A policy is only as good as its fit with this list, so this step decides everything else.
Be specific. “Dad takes something for his blood pressure” is not enough — you need the condition, the medicine, and how stable it has been. Insurers ask exactly these questions during medical screening, and your answers must match reality. If your parents are unsure about a detail, check with their doctor first — a short call now beats a disputed claim later.
The Cover That Matters Most for Older Travellers
For younger travellers, lost luggage or a cancelled flight is usually the biggest worry. For elderly parents, the priority flips: medical cover comes first, and everything else is secondary. Look for four things in every policy you consider: emergency medical expenses with a limit high enough for the destination, emergency medical evacuation to the nearest suitable hospital, repatriation home by air ambulance or escorted flight, and a 24-hour emergency helpline you can actually reach. If a policy is vague about any of these four, treat that as a warning sign and move on.
Pre-Existing Conditions: Declare Everything
This is the single most common reason travel insurance claims are refused: a medical condition that existed before the trip was never declared. Declare everything — even conditions that feel minor, long-standing, or fully controlled by medication. Diabetes, high blood pressure, a knee replacement five years ago, mild asthma: if it is on your parents’ medical record, it belongs on the application.
Answer every screening question honestly. A higher premium for a declared condition is always better than a refused claim for an undeclared one. If an insurer will not cover a particular condition, ask whether they will cover the rest of the trip with only that condition excluded — many will. Keep a copy of the medical declaration and the policy wording, so you can prove exactly what was disclosed if you ever need to claim.
Age Limits and Medical Screening: What to Expect
Some standard policies stop covering travellers above a certain age, or charge much more once a traveller passes it. That does not mean your parents cannot be insured — it means you may need a specialist provider that focuses on older travellers, where medical screening is a normal part of the process.
Screening usually means an online questionnaire or a short phone call, so be ready with the list you made earlier. After a recent hospital stay, a new diagnosis, or a change of medication, the insurer may ask for a doctor’s note confirming they are fit to travel — extra work, but it makes a disputed claim much harder. Buy the policy as soon as the trip is booked: cancellation cover only protects you from the day the policy starts.
Trip Cancellation and Interruption Cover
Medical cover protects your parents abroad. Cancellation cover protects the money you have already spent if the trip cannot go ahead. Check that the cancellation limit covers the full prepaid cost — flights, hotels, tours, everything — and read which reasons are covered. Illness of a traveller or a close family member is usually covered; changing your mind is not.
Also check the excess, the amount you pay yourself on each claim. A policy with a low premium and a very high excess can leave you paying most of a small claim yourself. For a family trip with elderly parents, a moderate excess on a policy with a solid medical limit is usually the better trade.
Match the Policy to the Trip
A policy that fits a weekend city break may not fit a three-week trip with a cruise and a remote island stay. Check the destination, the activities, and the trip length against the policy — healthcare costs vary sharply by destination, and some policies set lower medical limits for certain regions or exclude specific countries.
If your trip includes a cruise, you need cruise cover — a standard policy often excludes medical care on board a ship and the cost of being evacuated from it. And the destination itself deserves the same careful thought: comfort, easy transport, and quick access to healthcare matter far more for older travellers than ticking off sights, so look for places that work well for senior travellers rather than the most famous ones.
How to Compare Policies Side by Side
Do not compare policies by price alone. Check the same points on each option: the emergency medical limit, evacuation and repatriation included rather than optional, every pre-existing condition declared and accepted in writing, a cancellation limit covering the full prepaid cost, activities on your itinerary covered, the excess on medical and cancellation claims, a 24-hour helpline, and how claims are made. The cheapest policy that fails two of these checks is not a bargain — the right one answers every question on this list clearly, in writing, before you pay.
The Journey Itself Needs Planning Too
Insurance covers emergencies. Comfort on the journey is a separate job, and it matters just as much. Book aisle seats near the front of the plane so your parents can stand and stretch easily. Keep all medication in hand luggage, in its original packaging, with a copy of the prescription. Pack a small bag with water, snacks, and anything they need within reach.
The same careful flight planning applies when you travel with children — our guide to travelling with kids on a long-haul flight covers seat choice, packing, and sleep on a long journey, and much of that thinking transfers directly to a long flight with elderly parents. Plan rest breaks into the first day instead of rushing to sightseeing — a slow first day prevents an exhausted second one.
Common Mistakes to Avoid
The first mistake is buying on price alone. A policy that costs very little usually covers very little, and the gap only shows up when you need it most. The second is assuming other cover is enough. A European Health Insurance Card or its replacement is not a substitute for travel insurance: it does not cover private treatment, repatriation, or cancellation.
The third mistake is leaving insurance until the last day. Buy it when you book, read the exclusions before you travel, and carry the policy number and helpline number in your phone and on paper. If something goes wrong, call the helpline before paying any large medical bill yourself — they can often arrange direct payment with the hospital.
FAQ
Can I buy travel insurance for parents over 80?
Yes. Specialist insurers cover travellers well into their 80s and beyond — expect a medical screening questionnaire and a higher premium, and buy early so cancellation cover starts when you book.
Do my parents need insurance if they are healthy?
Yes. Good health does not prevent accidents, a fall on uneven ground, or a sudden illness abroad. Without insurance, even a short hospital stay overseas can leave you with a very large bill — repatriation alone can cost more than the whole holiday.
Final Thoughts
Choosing travel insurance for a trip with elderly parents is not a formality to rush through at checkout — it is the one part of the trip that protects everything else. Start with their health, declare every condition, check the medical limit and the evacuation cover, and compare policies on what they actually include rather than what they cost. Do that, and the trip can be what it should be: your parents enjoying the journey, and you enjoying it with them.